Navigating the Home Buying Journey
Having a to-do list in the Reminders or Notes app on your phone also isn’t a bad idea. There’s a lot to do; don’t expect your brain to keep it all straight. Enjoy the process as much as you can (remember, this is a good thing) and pop some champagne when it’s over.
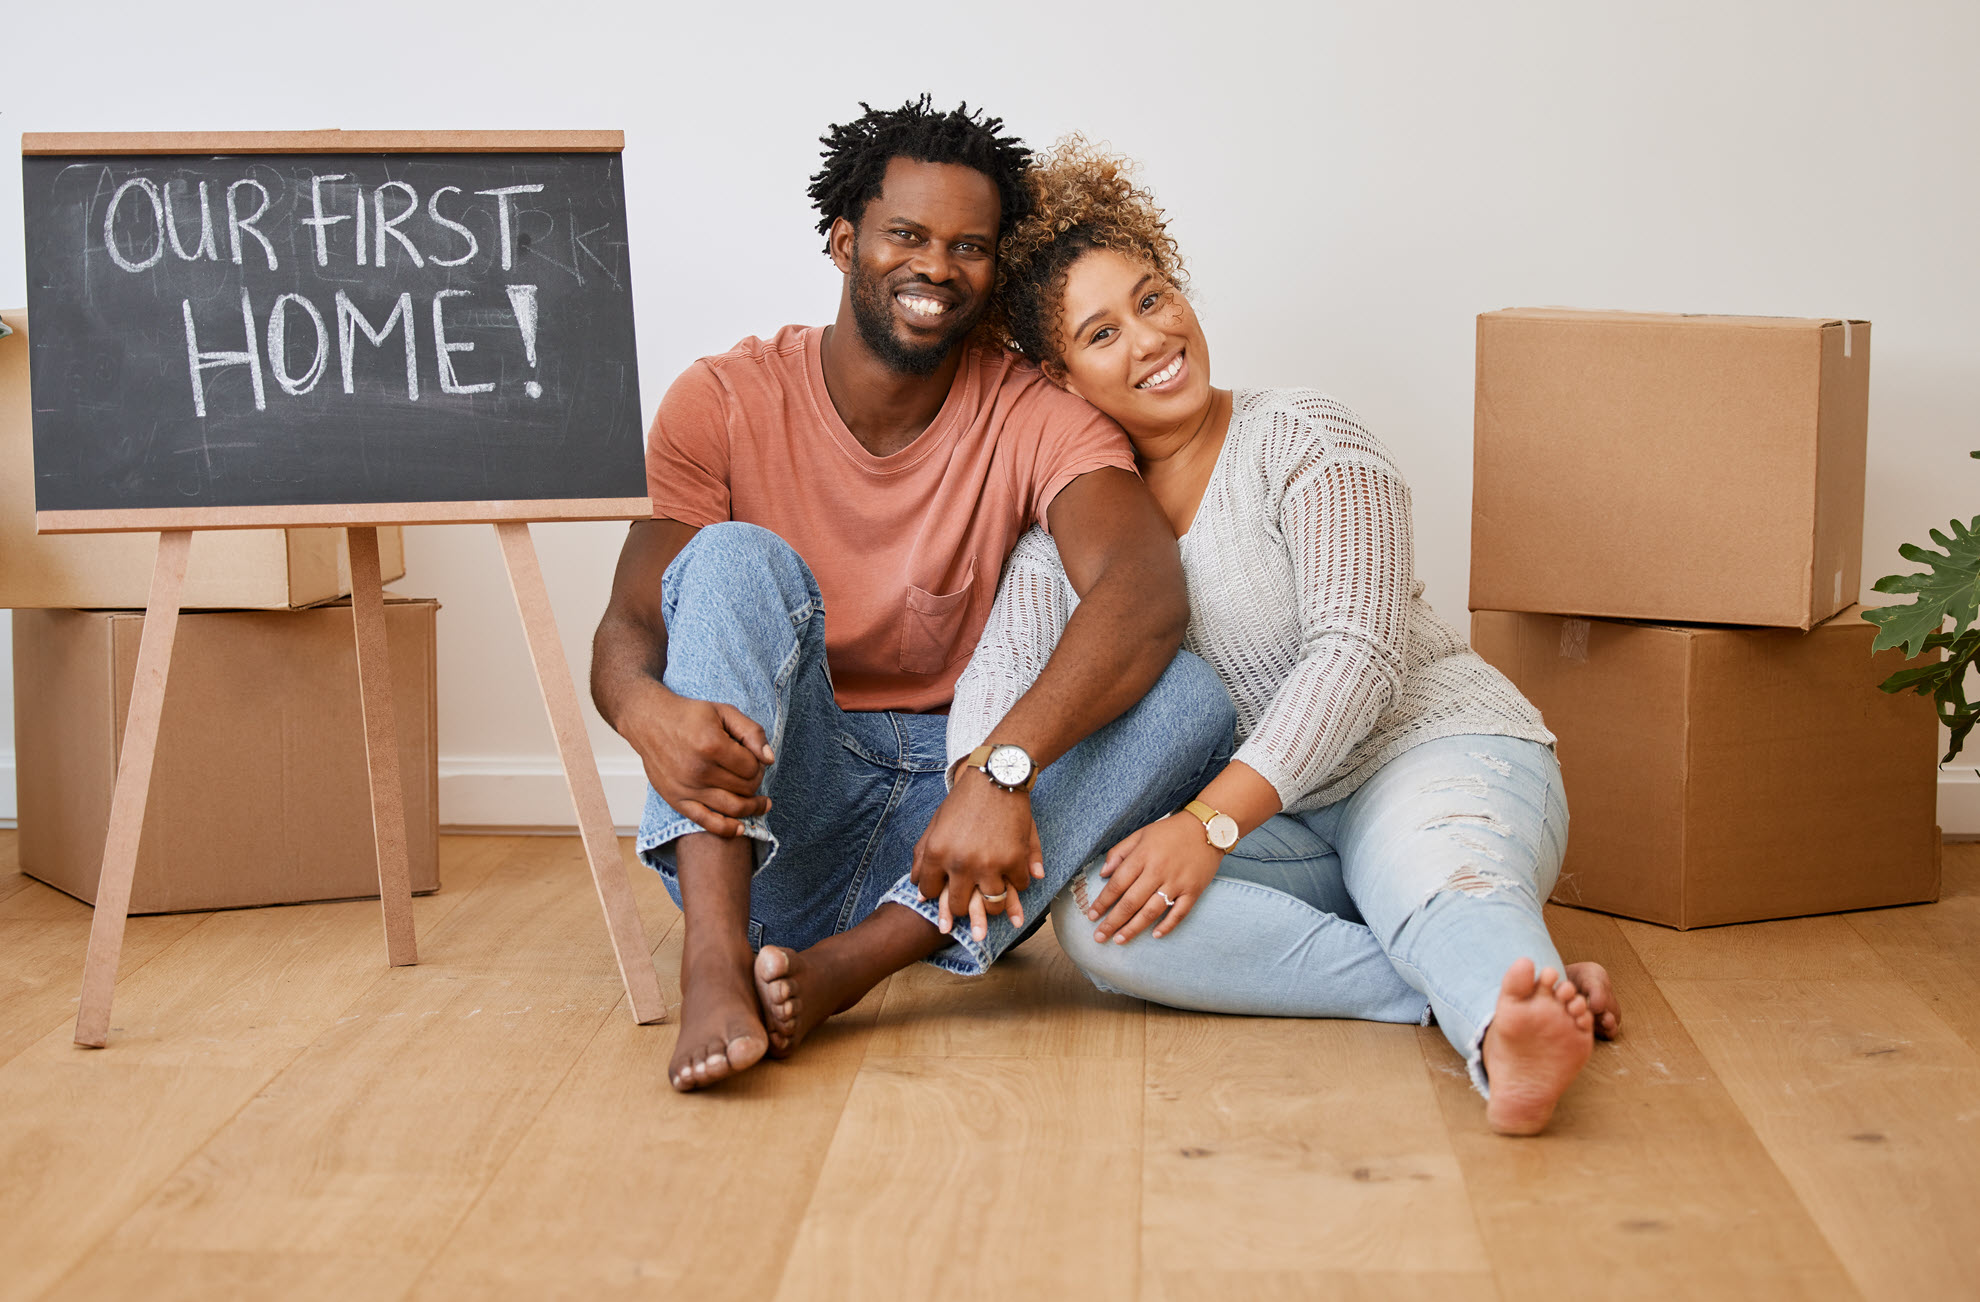
I’m in the middle of buying a home for the first time, and it is a journey that I wasn’t mentally prepared for. There are things that I understood would need to happen from a broad perspective, but it’s different being in the nitty-gritty. The process is both easier and more complicated than I thought. Here’s what I mean:
Step 1: Find the house
This is the most enjoyable part. If you scroll Zillow for fun, you know what I’m talking about. Once you find a house that you’re serious about, you’ll need to set up a tour. You can do this on your own, but it’s better to do it with a buyer’s agent. Which brings us to…
Step 1.5: Find an agent
If you’re more organized than I am, this is probably step 1. If you’re like me and your semi-casual house browsing turned into a serious home-buying venture, then this is where finding an agent gets inserted. This is not a step to be taken lightly; your agent will be with you all the way to closing. They should be someone you trust, especially if you’re ignorant to the home-buying experience, so ask your parents or other family members/friends if they know anyone or have used an agent that they would recommend.
Step 2: Tour the house
In fact, tour a few. Tell your agent what you’re looking for and let them set up a few viewings for you. Even if you don’t think a certain house is a place you’ll want to live, you’ll be surprised how much you can learn – not only about houses and the process but also about what’s important to you in a home. Once you’ve decided on a house, there’s one more thing you need to do before making an offer.
Step 3: Check your bank account
If your real estate agent is like mine, she’ll give you an estimated cost breakdown of the home-buying process. Make sure you’re budgeting for it.
Step 4: Make an offer
Talk it over with your real estate agent and decide what amount you want to offer the seller. Also decide what amount you’re willing to go up to in case the seller doesn’t accept your initial offer. Your agent will write up a contract and send it to the seller’s agent – from this point on any contact with the seller should be between your agent and theirs. Then you wait.
Step 5: Offer acceptance
Once you and the seller have landed on an acceptable offer and sign the agreement, part 2 of the journey begins. Starting with paying the seller “earnest money” – a deposit made in good faith that shows you’re serious about buying the house. It’s typically 1 – 3% of the purchase price.
Step 6: The to-do list
There are five things that need to get done before closing. Simple enough right?
- Schedule the inspection: find an inspection company (or ask your agent to recommend one) and get the inspection scheduled as soon as possible. You want to make sure there isn’t anything lurking under the surface of the house that would keep you from moving in. You’ll typically want the full home inspection plus sewer, radon, mold, and pest.
- Find a mortgage lender: meet with a mortgage lender, or a few to shop around on rates. They will ask for a lot of information from you. It will be an ongoing process to get to a mortgage approval. Be prepared to provide pay stubs, account statements, tax returns; basically, anything that has to do with your finances. They’ll also pull your credit, which means your credit score will take a hit.
- The title company: this one was pretty simple for me, at least so far. I chose one from a list my agent sent me, she set it up, and all I had to do was sign some forms online.
- Homeowner’s insurance: this was also relatively painless, thankfully. My dad recommended an insurance agent, so I didn’t have to shop around. The insurance company primarily worked with the mortgage lender to get the information they needed, so not a lot of extra effort on my end.
- The appraisal: once you’ve been approved for a mortgage, the lender will order an appraisal on the house. This will tell you how much the house is actually worth (hopefully it’s more than what you’re paying for it).
Step 7: The inspection
The inspector will walk around the house with you checking for things that aren’t up to snuff. Spoiler – there will be things wrong with the house. The question is what you can live with, what you want fixed, and what would absolutely keep you from moving in. Be prepared to spend 2 – 3 hours with the inspector. Once you have the results, you have the opportunity to ask the seller to fix some of the issues, see if they’ll drop the purchase price, or offer seller’s assist so you can do the fixing.
Step 8: Closing
Your inspection is done, negotiations are over, your mortgage, insurance, and title are all set up and ready for closing. Now you’re on to part 3; the move.
- Make sure you know when the seller is moving out (if they still live in the home), it might not be the same day as closing
- Pack up all your stuff (the worst part)
- Get moving (literally)
- Set up utilities
- Close up shop at your old place (terminate your lease, turn off utilities, etc.)
- Live in your new house (yay!)
Step 9: Change your address
- At the post office
- On your driver’s license
- With your job
- Bank accounts
- Credit cards
- Subscriptions
- Anywhere else I forgot about
My best piece of advice is to save everything. Create a Google Drive folder for the house, and any time you sign or receive documents from your agent, lender, title company, insurer, or inspector – save it. Having a to-do list in the Reminders or Notes app on your phone also isn’t a bad idea. There’s a lot to do; don’t expect your brain to keep it all straight. Enjoy the process as much as you can (remember, this is a good thing) and pop some champagne when it’s over.
This information is intended for informational and educational purposes only and is not individual investment or tax advice. Investing involves risk, principal loss is possible.
Please remember that I am not an investment advisor nor am I a portfolio manager, but I can introduce you to a few.
More information on how we treat your information is available in our Privacy Policy.